Are you tired of traditional banks offering paltry interest rates on your savings while charging exorbitant fees for loans? Enter Zonky, the peer-to-peer lending platform that promises to flip the script and bring a breath of fresh air to personal finance. But with myriad options available in the crowded fintech space, how do you know if Zonky is truly worth your time (and money)? In this comprehensive review, we’ll dive deep into what makes Zonky tick—its unique features, benefits, potential risks, and real user experiences. Whether you’re looking to invest or seeking a loan without breaking the bank, join us as we unravel whether Zonky lives up to its hype or falls short in delivering financial freedom!
What is Zonky and how does it work?
Zonky is a peer-to-peer lending platform that connects borrowers in need of loans with individual investors looking to earn a return on their money. It was founded in 2015 by Czech entrepreneurs and has since become one of the leading P2P lending platforms in Europe, with over €1 billion lent out to date. The concept of peer-to-peer lending is based on the idea of cutting out traditional financial institutions such as banks and connecting individuals directly. Zonky acts as an intermediary between borrowers and investors, facilitating the loan process and ensuring fair terms for both parties. Zonky provides an easy and transparent way for individuals to borrow money or invest in loans without involving traditional financial institutions. It also offers competitive interest rates for both borrowers and investors, making it a popular choice in the peer-to-peer lending market. So if you are looking for an alternative way to borrow or invest money, Zonky could be worth considering.
The benefits of peer-to-peer lending
Peer-to-peer lending opens up new avenues for both borrowers and investors. It connects individuals directly, bypassing traditional banks. This can lead to lower interest rates for borrowers and higher returns for investors. Investors have the opportunity to diversify their portfolios with relatively small amounts of capital. By funding multiple loans, they spread risk across different projects or borrowers. For borrowers, P2P platforms often provide quicker access to funds compared to conventional lenders. The application process is usually streamlined, making it easier for those in need of immediate cash flow. Moreover, peer-to-peer lending fosters a sense of community. Investors can choose specific projects that resonate with them personally or support local businesses they believe in. Transparency is another key benefit; many platforms provide detailed information about loan recipients and their financial situations, allowing informed decision-making on where to invest your money.
How to get started with Zonky
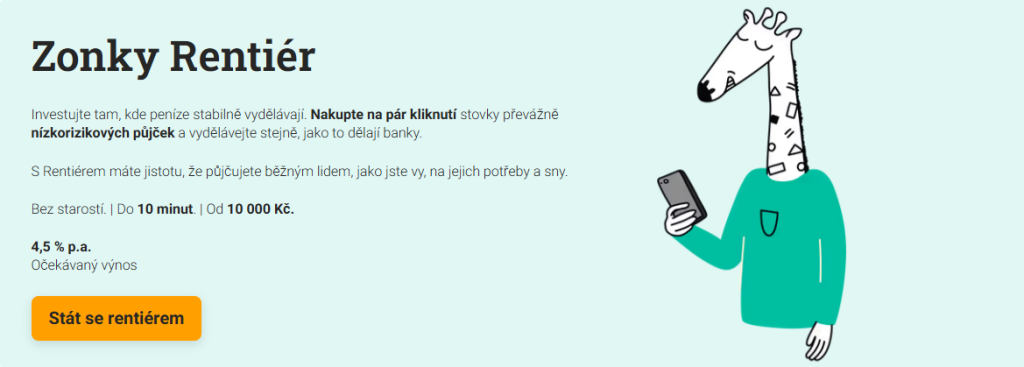
Getting started with Zonky is a breeze. First, visit their website and create an account. You’ll need to provide some basic information such as your email, name, and phone number. Once registered, verify your identity to comply with regulations. This step typically involves uploading identification documents like a passport or ID card. Next, link your bank account for seamless transactions. Zonky uses this connection to manage deposits and withdrawals securely. After everything is set up, you can explore available loans on the platform. Each loan comes with details about the borrower’s profile and purpose of the loan. To invest, decide how much you want to allocate towards different loans based on risk levels that suit your strategy. Then simply start investing! As borrowers make repayments, you’ll begin seeing returns on your investment over time.
Zonky’s interest rates and fees
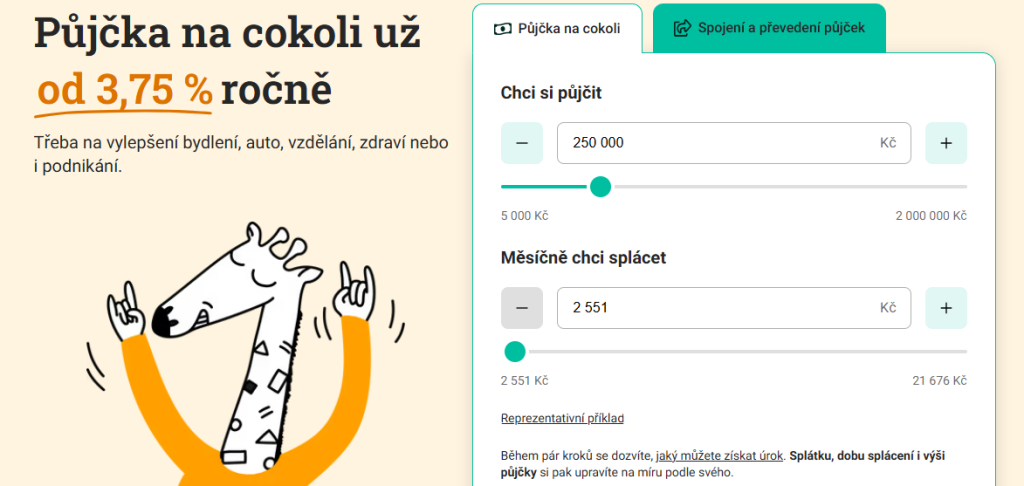
Zonky offers competitive interest rates that can attract both borrowers and investors. Rates vary based on the borrower’s creditworthiness, which means more reliable borrowers might secure lower rates. This dynamic creates a balanced opportunity for lenders looking to earn returns. Fees are another important consideration. Zonky charges an origination fee on loans, typically calculated as a percentage of the loan amount. This fee is often factored into the overall cost for borrowers but does not directly impact lenders’ earnings. Investors should also be aware of potential fees associated with their accounts, such as withdrawal or management fees. Transparency about these costs is crucial when making investment decisions. Understanding how interest rates and fees work can help you strategize your investments effectively while ensuring you’re maximizing your returns over time.
Customer reviews and success stories
Zonky has garnered a variety of customer reviews, showcasing the diverse experiences of its users. Many investors appreciate the platform’s user-friendly interface and straightforward lending process. Success stories often highlight borrowers who have found relief through Zonky loans. People share how they funded home renovations or consolidated debts with ease. These testimonials illustrate real-life impacts that go beyond mere numbers. Investors too have reported positive returns, emphasizing the importance of careful selection in loan projects. They frequently mention feeling empowered by directly contributing to someone’s financial journey. However, it’s essential to read reviews with a critical eye. Some customers express concerns about late payments or defaults—challenges inherent in peer-to-peer lending. Each review adds a layer to understanding Zonky’s overall performance as an investment option within this growing marketplace.
Tips for successful investing on Zonky
Diversification is key. Spread your investments across multiple loans to mitigate risks. This tactic helps protect your portfolio against individual defaults. Research borrowers thoroughly. Take the time to read their profiles and understand their needs. Knowing who you’re lending to can make a significant difference. Set realistic expectations for returns. Peer-to-peer lending isn’t a get-rich-quick scheme, but rather a steady way to grow your wealth over time. Keep an eye on economic trends that could impact borrower repayment ability. Stay informed about market conditions and adjust your strategy accordingly. Finally, be patient with your investments. Allow them time to mature while avoiding hasty decisions based on short-term fluctuations in the market or personal emotions around money matters.
Conclusion: Is Zonky a good choice for investors?
When considering Zonky as a peer-to-peer lending platform, it’s essential to weigh both its advantages and disadvantages. Zonky offers an innovative way for investors to participate in the lending market while also providing borrowers with access to funds in a more streamlined manner. The platform’s user-friendly interface makes it easy for anyone to start investing. Investors can benefit from attractive interest rates and have flexibility over how much they invest. Success stories abound, illustrating that many users have enjoyed positive experiences earning returns on their investments. However, potential risks do exist, such as borrower defaults and economic fluctuations that could affect repayment. In comparison with other platforms, Zonky stands out due to its community-driven approach but may not be the best fit for everyone. Those interested should consider their personal risk tolerance and investment goals before diving in. For those ready to explore peer-to-peer lending further, Zonky presents itself as a viable option worth exploring. Whether it becomes an integral part of your investment portfolio or serves merely as a stepping stone into this alternative financing world depends largely on individual preferences and strategies.